Picking up a few DoorDash deliveries after work, driving for Uber on the weekends, or making grocery deliveries can be a convenient way to earn extra income.
But there’s one question many people don’t think about until after they’ve already started:
Does my personal auto insurance cover me while I’m working?
The answer isn’t always simple.
When you start using your personal vehicle to earn money, how you use it changes. Depending on your policy, your employer, and your state, your personal auto coverage may not apply the same way it does during everyday driving.
Personal Driving vs. Business Use
A typical personal auto insurance policy is designed primarily for personal use, such as:
- Driving to and from work
- Running errands
- Taking kids to school or activities
- Visiting friends and family
- Personal road trips
Using that same vehicle to transport passengers, deliver meals, carry groceries, or make other paid deliveries introduces a business use that may require different coverage.
That doesn’t automatically mean you need an entirely separate commercial auto policy. But it does mean you should talk with your insurance agent before assuming your existing policy covers everything.
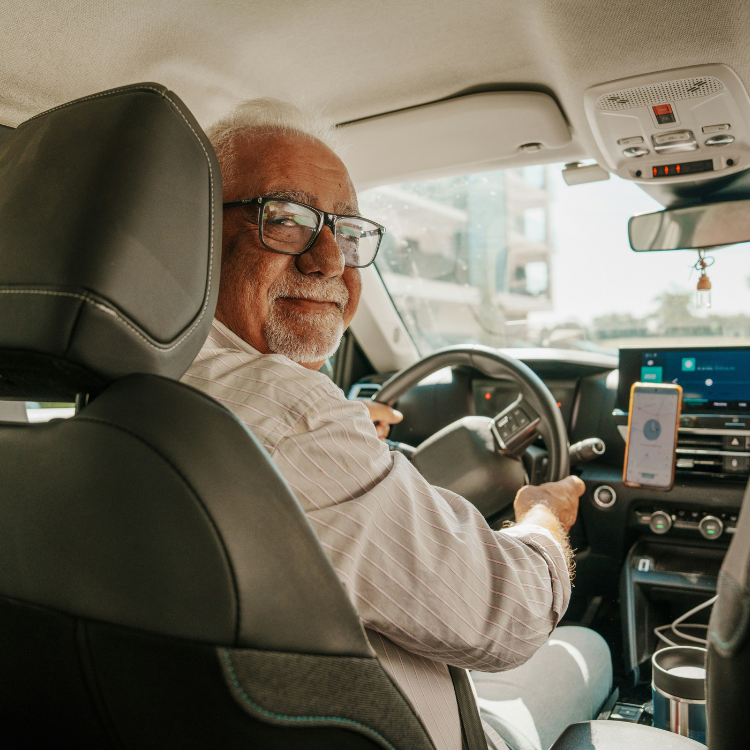
Driving for Uber or Lyft
Rideshare driving is a good example of why coverage can become more complicated.
When you drive for a rideshare service, your coverage may vary depending on what you’re doing at the time of an accident.
For example, you could be:
- Driving for personal reasons with the app turned off
- Logged into the app and waiting for a ride request
- Driving to pick up a passenger
- Transporting a passenger
Your personal auto policy, coverage provided by the rideshare company, or a rideshare endorsement may apply differently during each stage.
The important thing is to understand those differences before you start driving, rather than discovering a gap after an accident.
What About DoorDash, Instacart, and Other Delivery Services?
Delivery driving creates similar questions.
If you use your vehicle to deliver restaurant meals, groceries, packages, or other goods for pay, that activity may fall outside the type of use covered by a standard personal auto policy.
Some insurers offer endorsements for delivery or business use, while others may require a different policy altogether.
Coverage from the delivery platform can also vary, so don’t assume your employer automatically provides everything you need.
What Could Happen If Your Insurance Doesn’t Know?
If your insurer doesn’t know you use your vehicle for paid driving, you could face coverage issues after a claim.
That’s why transparency matters.
Tell your insurance agent:
- What company you drive for
- Whether you transport passengers, food, groceries, or packages
- How frequently you drive
- Approximately how many miles you drive for the side income
- Whether the platform provides any insurance while you are working
From there, your agent can help determine what your existing policy covers and whether you need an endorsement or a different type of coverage.
Does the Company I Drive for Provide Insurance?
Some rideshare and delivery companies provide certain insurance protections while drivers are actively using their platforms.
However, those protections can have different limits, deductibles, requirements, and exclusions depending on the company and situation.
Think of platform-provided insurance as one piece of the picture, not a replacement for understanding your own auto policy.
Review both so you know how they work together.
What About an Accident While You’re Off the Clock?
If you’re using your car for ordinary personal driving and aren’t actively working through an app or delivery service, your personal auto insurance will generally respond under your policy’s terms.
The complication comes when the vehicle transitions from personal use to paid use.
That’s why your agent needs to know how you’re actually using the car.
A Side Hustle Can Change Your Insurance Needs
There’s nothing wrong with using your vehicle to earn extra income. Plenty of people do.
But when you change how you use your vehicle, your insurance may need to change.
Before you begin driving for Uber, Lyft, DoorDash, Instacart, or another delivery or rideshare company, take a few minutes to review your auto policy.
Ask:
- Does my personal policy allow this type of use?
- Is there a rideshare or delivery endorsement available?
- When does the platform’s insurance apply?
- Are there gaps between my personal and platform coverage?
- What happens if my vehicle is damaged while I’m working?
Know Before You Drive
The best time to understand your coverage is before your first delivery or passenger pickup.
At Crunelle Insurance, we can help review how you use your vehicle, explain your current coverage, and determine whether anything needs to change before you start earning income on the road.
Insurance requirements and available coverage vary by carrier, platform, and state, so reach out before you assume your personal policy covers you.
Making Money From Home? Read Our Guide to Side Hustles & Home Insurance